The Debt Dilemma : Sovereign Debt and the AI Pivot
Now-a-days understanding the nuances of the bond market is very essential to understand wellness of global economy because most of countries are in an initiative to increase debt or already incurred mammoth size debt. Now we know how to create currency from thin air and in near future we might learn to play with debt with our adept in creating financial strategies. Although the subprime crisis taught us many valuable lessons, they are clearly not enough when we continue to approach the debt market so fearlessly. The ultimate crisis begins when a nation fails to achieve economic growth even after accumulating massive debt. Gradually, the trajectory of Artificial Intelligence may dictate the future of nations simply because we are running out of other options.
Economic Growth Trends
Canada monthly GDP growth data showed 0.2 % expansion, revealing that July to August period showed more vulnerable face of the economy because expansions in service and utility sectors offsetted by contraction in retail and manufacturing sector. Canada as a economy have strong Service and SME sectors but the ongoing tariff crisis might invite significant challenges to export prospects of the country because as per the available information from Reuters[i] shows that 66% to 72 % of the Canadian exports goes to United states. The welcome move of three capacity expansions like adding oil pipeline[ii] capacity for 1 million barrels per day in export capacity, $33 billion expansion of LNG facility[iii] in Kitimat and increasing 900 megawatts[iv] new computing capacity for Canadian AI infrastructure shows that country have prospective expectations for its economy.
The GDP data of QoQ showed that, after three quarter of dismal performance, the last two quarters of UK shows the resurgence of economy. The GDP data YoY showed 1.4 % expansion for the second quarter in 2026 was mainly supported by the 1.7% growth in service sector. The construction sector fell by 1.0% shows that the massive skill shortage together with high insolvency rates and strict net zero carbon rules had impacted the sector growth. Despite ranking 25th in global oil production, the UK will not escape the backlash of surging oil prices because the country remains a net importer of crude oil. The UK initiative for open talks with European allies over realising of emergency supplies[v] might a measure to tackle the surge in oil prices.
The GDP growth rate in USA for the second quarter showed 2.2 % expansion compared with 2.5% expansion in the previous quarter. The 3.8 % rise in consumer spending[vi] and 2.8 % growth in GDP sales shows that the economy is more dependent on the internal growth rather than external growth. This infact reveals the resilience nature of USA economy because globally the country enjoys the number one rank in consumer spending. The sharp slow down in the US labour market may be the next major challenge the economy faces. Meanwhile Russia continued to grow at a snail pace amid the ongoing war with Ukraine with 0.8% expansion.
Inflation and Interest rate
The inflationary pressure continue to disturb the global economy while monthly data of few countries shows decline in inflation but the year on year data or core inflation continue to increase. The decline in monthly inflation might be due to strict inflation targeting measures which reveal the eagerness in controlling inflation within permitted levels. The rise of interest rate by most of developed countries to control inflation show the urgency of the issue to address with right decision. Last week Australian government also increased interest rate with 25 bps and the current interest rate in Australia is 4.6%. The negative monthly inflation figure at -0.3 in France reveal more about its structural issues than the inflation control measures since the mounting of debt to GDP ratio roughly around 119% to 122% is far exceeding the European union 60% ceiling. The decline in inflation is mainly attributed to drop in service prices after the summer period. The increasing trend in inflation were noticeable in Germany and Italy while the negative growth of inflation for MoM at -0.4 in south Africa shows the significant challenges the south Africa economy faces due to high unemployment and failing infrastructure.
Business Trends
The rise in new car registration in Italian car market at 9.9 % shows that demand had resurfaced after two months of negative performance. On the other hand great Britain showed slight reduction in new car registration at 12% compared with 13.7% in the previous month. Interestingly France continued its healthy trend in new car sales at current rate 11.6 % compared with 7.4% growth in the previous month. The Current industrial profit data at 15.7 % published by Chinese government failed to give any valid interpretation about Chinese economy because industrial profit had cyclical pattern starting the year to the year end. The rise of industrial production with marginal increase at 8% in India shows that industrial production trend maintained its status quo there by surprising the consensus figure and TE forecast at 6.5% and 5.5% respectively. The surge in industrial production at 15.4% for YoY data for Singapore data shows that semi-conductor and biomedical manufacturing is performing well since the Singapore manufacturing is heavily anchored on these two sectors.
World Stock Markets
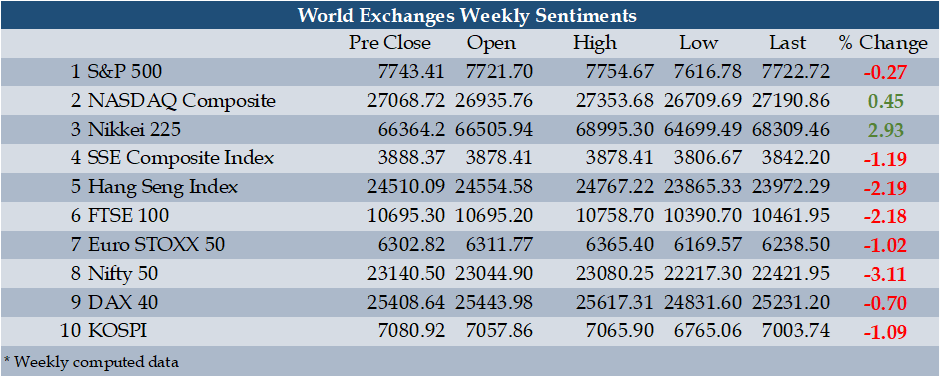
Bearish sentiments dominated in most of world stock market and market remained red for the week. The crash in bond market spread to the equity market because investors found no alternative in equity since they believed that rise in interest rate coupled with inflationary pressure may further squeeze the corporate profits. Contrary to popular bearish sentiments , Japan stock market registered 2.93 percent gain for the week. The ongoing optimism in AI and semiconductor stocks really influenced the sentiments of Japan investors because they perceive that selling in bond market might infuse more funds to equity markets. Nikkei index is heavily weighted towards semiconductor and AL tech giants stocks. Indian stocks markets continued its negative sentiments and registered 3.11% decline for the week. The outflow of FII investors coupled with weak Indian rupee influenced the sentiments.
Forex Market
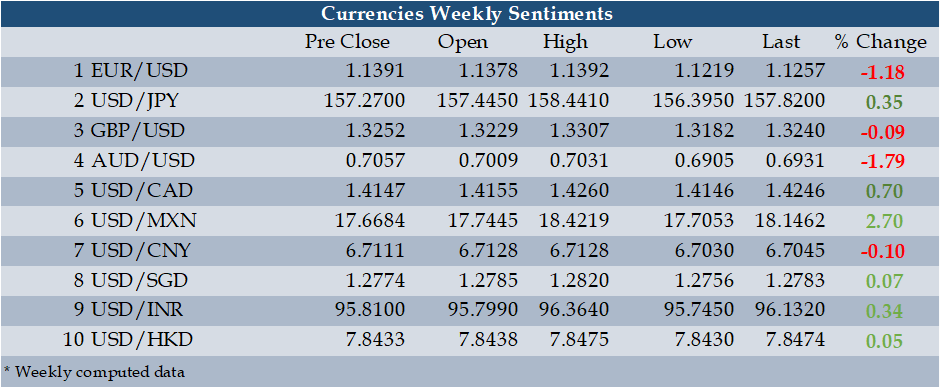
Mixed sentiments reflected in the currency market and out of the major currency pairs Mexican Peso and Australian dollar showed major weakness against dollar even though dollar strengthened against most of major currencies. Contrary to major trend, Chinese yuan strengthened against dollar might be signifying that, FII investor fund flow toward Chinese market is one of the factor that is strengthening Chinese yuan. It is believed that USA and China will be the major stakeholder for the expected AI revolution. Singapore dollar also exhibited similar sentiments because strong participation in semi conductor business backed by strong economic fundamentals together with safe heaven appeal.
Commodities Market
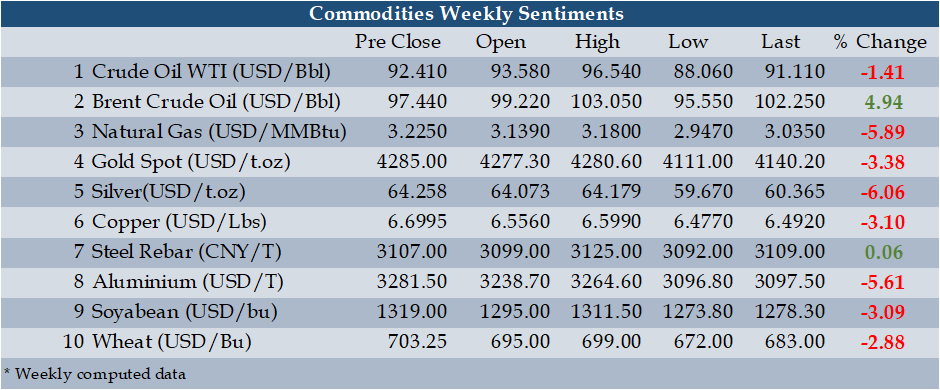
Bearish Sentiments with heavy selling noticed in most of the majorly traded commodities. Gold prices continued to plunch carrying over the sentiments of last six weeks. Failure to repose the safe haven appeal might have contributed to the fall in prices but major negative sentiments in the commodity market might have happened because most of developed countries have raised the interest rate to control inflation. The might have created downward pressure on commodities especially industrial metals.
Disclaimer
The views are expressed for the purpose of study only and not an advice to any traders or investors in the market. Trading/investing in Financial markets involves considerable risk and you may lose part or all of the initial investment. It is not ideal for all types of investors, and you are advised to seek professional assistance before the same. The news and views posted on this report are based on information, which are believed to be accurate. The author cannot be held responsible for the accuracy of the content posted on this report or for decisions taken by the readers based on such information.
References
[i] https://www.reuters.com/world/americas/canadas-trade-deficit-narrows-december-share-exports-us-shrinks-further-2026-02-19/
[ii] https://www.rigzone.com/news/wire/canada_pm_invokes_new_powers_to_fasttrack_oil_pipeline-02-oct-2026-184763-article/
[iii] https://www.shell.com/news-and-insights/newsroom/news-and-media-releases/2026/shell-takes-final-investment-decision-to-double-lng-canada-capacity.html
[iv] https://www.canada.ca/en/innovation-science-economic-development/news/2026/09/government-of-canada-welcomes-major-new-investment-in-sovereign-ai-infrastructure-in-saskatchewan.html
[v] https://www.theguardian.com/money/2026/oct/02/uk-diesel-price-record-high-iran-war-oil
[vi][vi] https://abcnews.com/Business/wireStory/us-economy-grew-solid-22-quarter-government-upgrading-136885737