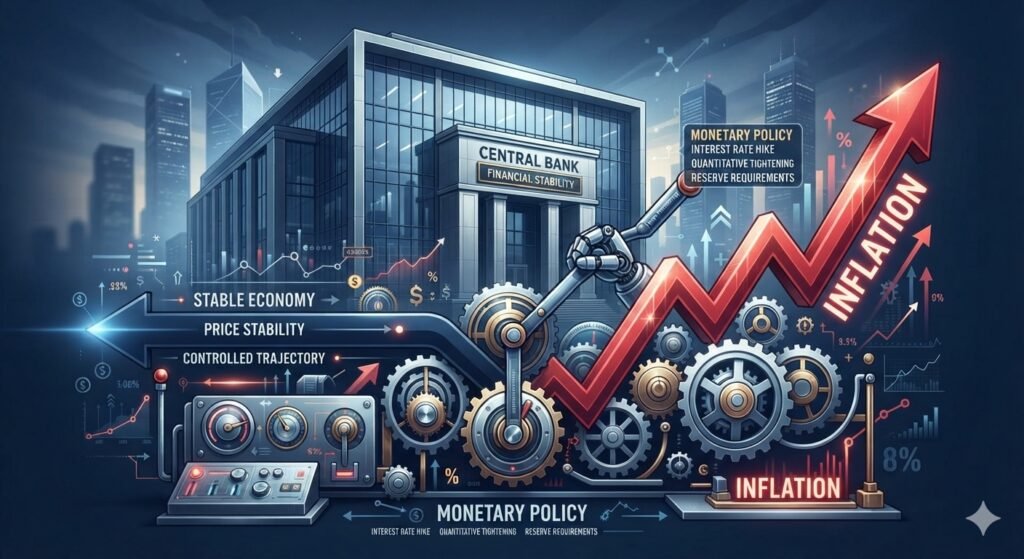
The Policy makers started systematic intervention against rising inflation
Published on 13 October 2026
The policy makers all over the world reviewed that inflationary pressure continue to remain elevated, if the middle east crises continue to destabilize the rhythm of global economy. The European Central bank policy makers observed that the upside trend in inflation may continue and instructed for cautious approach towards economy without any further policy changes. Meanwhile the decision of Bank of Japan to increase the interest rate at 1.25% in last September is expected to increase the borrowing cost to its highest level since 1995. In Great Britain the Monetary policy committee assessed that the main reason for the rise in inflation in Great Britain is because of middle east crisis. Developing countries like Mexico revealed that its anxiety is more inclined to growth prospects than inflationary pressure of the economy and further change in US economic policy or worsening of middle east war between Iran and Israel might bring more uncertainty to its economy.
Business trends
The marginal decrease in manufacturing index of Australia, Japan, Singapore and Brazil shows the slight weakness of manufacturing sector. However countries like Spain, France, Germany, and Canada showing moderate increase in manufacturing activity. In USA , the Global S&P Composite PMI and ISM services business activity showed contradictory values about the state of economy and this is understandable when S&P composite PMI focus more on private jobs and ISM covers the broader non manufacturing activities. This states the strong trend of private jobs might be an adequate relief for the economy when overall weakness of broader economy posing challenges. Overall the global economy is continuing its moderate pace and slight variations in data is not adequate enough to predict a trend. The rise is non-oil private sector PMI data of Saudi Arabia shows that recovery of demand amid geopolitical uncertainty and supply chain disruptions. However the decline in industrial production continue to disturb the economy and the industrial production is on a negative phase since march. The sharp decline in German factory orders shows some genuine weakness in underlying industrial demand. The slight decrease in Brazil car production is just a pause in its expanding automobile sector since the data is not validated with the decreasing trend in new car registration. As per the data, the new car registration shows 2.3 % increase in registration.
Labor trends
The marginal decrease in job ads in Australia is not considered as a major indication since economic policy makers reviewed that the impact of rise in interest rate is not yet reflected in the economy because of the lag in labour economic nature to reflect it. The ADP employment data in USA showing continued marginal rise in private sector jobs and it might be an indication that the health care industries and hospitality industries in USA is not showing any genuine weakness since these sectors create more private jobs in USA. The cash earnings and overtime pay data published from Japan carried on its ongoing momentum where current data showed 3.8 % and 5.2% increase in these indicators. As per expert opinion marginal decrease in cash earnings compared to last month data is not a big concern because staying above with 3% increase shows that the trend is continuing. The declining trend in initial jobless claims shows the resilient nature of US economy to ongoing geopolitical risks. The slight increase in unemployment rate in Canada might be because of the increase in interest rate. The negative growth in employment for the last two months shows that Canadian economy started to reflect weakness but its too early to predict recessionary trends in the economy.
World Stock Markets
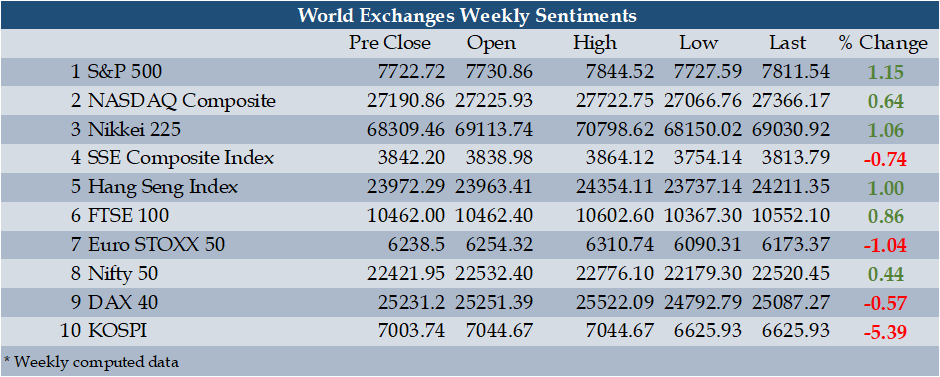
Overall mixed sentiments reflected in the stock market and investors traded mostly on domestic sentiments. The crash in south Korean stock market is mainly due to the tight competition in chip industry. The announcement of Chinese memory chip maker Chanxin Memory technologies about its new 4F2 memory cell architecture threatened South Korean tech giant lucrative DRAM duopoly. Apprehension of high AI valuations carried over the sentiments if cheap Chinese supply captures the market attention. Foreign investor massive selling to an estimated amount of 4.5 trillion drive the bearish sentiments when domestic investor buying demand failed to substantiate selling momentum. Flat movement noticed in Indian stock market and increase in repo rate by 25 basis point by RBI brought mixed sentiments in the market. Raising repo rate is considered as a adequate action because the monetary policy committee assessed that It is important to control the inflationary trend in the economy. Positive corporate earning sentiments from TCS and HCL technologies lifted the market mood and supported the prices from further erosion.
Forex Market
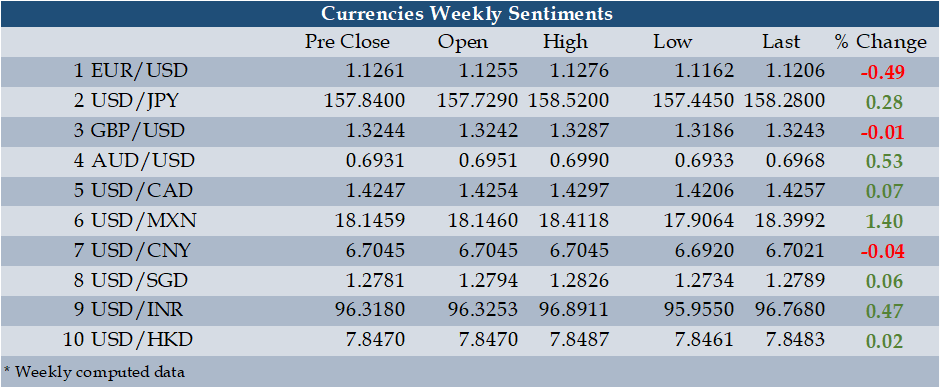
Forex market witnessed limited momentum because of the trend in raising the interest rate by 25 bps followed by most of developed nations and major economies. However the trend of strengthening of dollar continue to dominate the market sentiments. Among the currencies Mexican peso showed more weakness against dollar and Mexican central bank inaction in raising interest rate contrary to the ongoing trend followed by major nations favoured the dollar dominance.
Commodities Market
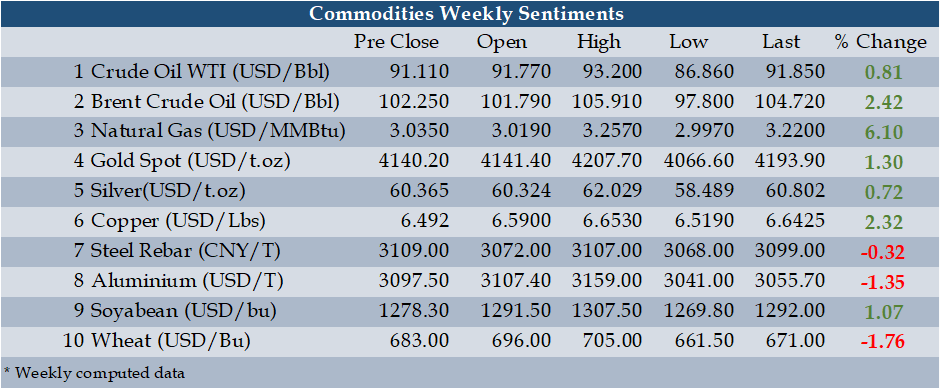
Mixed sentiments noticed in commodities market and rise in prices in crude oil mainly because of geopolitical tension in Middle east. The attack by Houthi militia targeting king Khalid international Airport in Riyadh might escalate the ongoing global energy crisis. The expectation of increased Russian supplies and softening of demand from Chinese refinery trends influenced the market sentiments. As expected the safe haven demand had brought positive mood in the precious metal market. Gold and silver prices ended with positive sentiments capturing the underlying market mood. Supply disruptions, structural AI-led demand and US tariff from loading influenced the market sentiments in copper and prices moved upwards with 2.32 % weekly gain.
Disclaimer
The views are expressed for the purpose of study only and not an advice to any traders or investors in the market. Trading/investing in Financial markets involves considerable risk and you may lose part or all of the initial investment. It is not ideal for all types of investors, and you are advised to seek professional assistance before the same. The news and views posted on this report are based on information, which are believed to be accurate. The author cannot be held responsible for the accuracy of the content posted on this report or for decisions taken by the readers based on such information.
References